Ditch: Pay Off Debt Faster

Screenshots
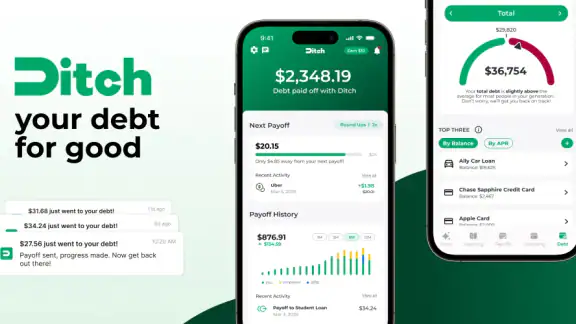
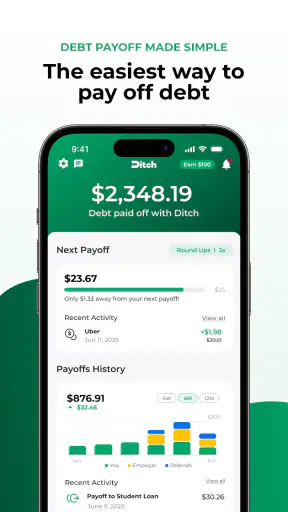
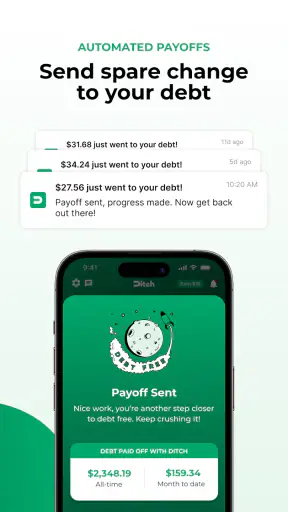
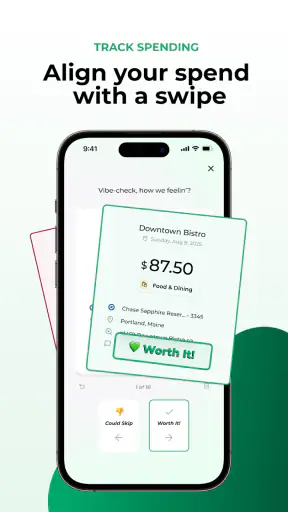
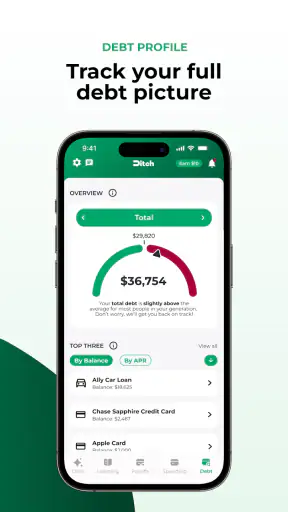
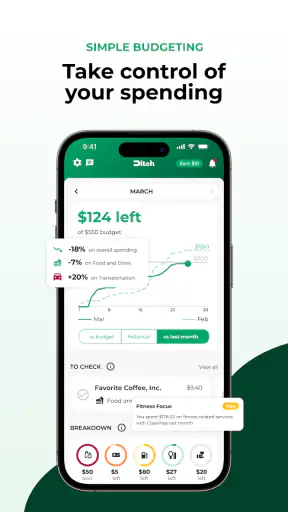
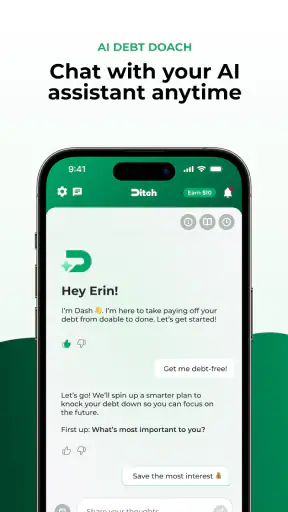
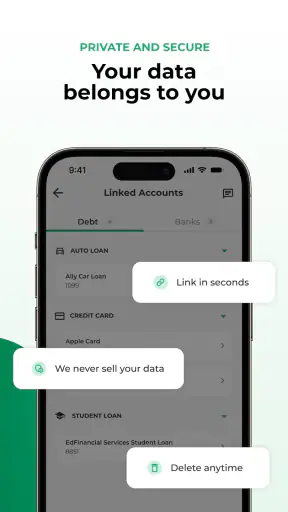
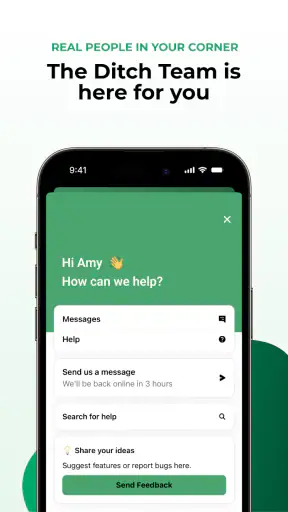
Details
- Rating
- 62.00 reviews
- Version
- 1.5.6
- Developer
- Ditch Technologies, Inc
Analysis by Norviv
Debt tools are easy to judge by their promises and much harder to judge by the moments when real money is involved. I approached Ditch: Pay Off Debt Faster with that in mind. It is a free finance app from Ditch Technologies, Inc, built around organizing debt and helping users move toward repayment rather than simply displaying balances. The store summary describes its purpose as automating payoff and tracking debt, but the useful question is whether that approach gives you enough control to make sensible decisions.
My overall impression is that Ditch is most appealing to someone who wants a focused repayment companion instead of a full banking replacement. It can help turn a vague goal such as “I need to get rid of this debt” into something you can review and act on. At the same time, I would not treat it as an adviser that can make personal financial choices for you. The quality of the experience depends on the information you enter, the choices you make, and how carefully you review any automated plan.
What Ditch is trying to solve
The hardest part of debt repayment is often not knowing that extra payments are useful. It is keeping several balances, due dates, interest costs, and competing priorities in view at the same time. A finance app that concentrates on payoff can reduce that mental load by giving the problem a dedicated place.
Ditch is designed for that narrow purpose. Rather than presenting itself as a general spending tracker, it focuses on debt payoff and progress. That distinction matters. If your main need is categorizing groceries or checking a complete household budget, a traditional budgeting app may be a better fit. If your immediate concern is understanding what you owe and maintaining a repayment routine, Ditch’s tighter focus makes more sense.
I also like the psychological advantage of a dedicated debt workspace. A bank app may show a credit-card balance, but it usually does not make the repayment journey feel like a project with a beginning, a plan, and visible progress. Ditch is useful when you need to return to the same goal repeatedly instead of checking a balance only when a payment is due.
The app is available at no upfront cost and is rated for Everyone, which makes it approachable for a broad audience. It has an average rating of 4.8 from around 1.1 thousand ratings, and more than 10 thousand installs. Those figures suggest that the concept has found an audience, although I would still judge the app by whether its controls and data handling suit your own situation rather than by popularity alone.
A practical scenario where the focus helps
Imagine that I have a credit-card balance, a personal loan, and a fixed amount left after rent and essentials each month. The usual alternative is to keep notes in a spreadsheet, open several lender apps, and manually decide where an extra payment should go. That can work, but it creates opportunities for outdated figures and missed reviews.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
With a debt-focused tool, I can begin by gathering the current details in one place, deciding how much I can realistically commit, and checking the plan whenever my circumstances change. The important benefit is not that an app magically creates spare money. It is that a repeatable review process makes the spare money I do have easier to direct.
I would use that process after payday, not every few hours. I would check whether the available amount is still realistic, confirm that essential bills are covered, and then review the repayment direction. That routine is more sustainable than setting an aggressive target once and abandoning it after an unexpected expense.
Trust starts with control, not promises
For a finance app, trust should come from visible choices. I want to know what I am being asked to enter, what the app is expected to do, and whether I can review or change an action before it affects my finances. Ditch’s core appeal is automation, but automation should never mean handing over judgment without a clear opportunity to inspect the result.
My advice is to treat setup as a review stage rather than a formality. Enter one debt at a time and check every figure before moving on. A misplaced decimal, an old balance, or an incorrect payment amount can make a repayment plan look more precise than it really is. The app can organize the information, but only I can confirm that the information reflects my current accounts.
This is also where user agency matters. A useful plan should support deliberate decisions, not pressure me into choosing the most ambitious payment. I would rather select an amount I can maintain through an ordinary month than promise an amount that leaves no room for transport, food, or an emergency. Debt reduction is a long process, and consistency is usually more valuable than a dramatic first step.
The developer, Ditch Technologies, Inc, presents the app as a finance product rather than a bank or lender. That distinction should shape how I use it. I would keep checking the original account or creditor for official balances, payment confirmations, and account notices. Ditch can be a planning and tracking layer, but the lender remains the authoritative place for the actual account status.
Automation needs a deliberate boundary
Automation sounds attractive because it can reduce repeated effort. It can also create a false sense that the work is finished. Before relying on any automated payoff behavior, I would want to understand exactly what is being scheduled, when it happens, which account is involved, and how I can pause or change it.
Those are not minor details. A payment that arrives late can lead to fees or other consequences, while an overly large payment can leave too little cash for essentials. I would therefore begin conservatively, use a modest amount, and watch the first cycle closely. Only after the process behaves as expected would I consider increasing the commitment.
I would also avoid treating an automated plan as permission to stop checking my creditor accounts. Statements can change, promotional rates can end, and unexpected charges can appear. A monthly review of both the debt account and the Ditch plan is a sensible safeguard, especially when the repayment strategy depends on changing balances.
Data-sensitive moments deserve extra attention
Any debt tracker involves information that I consider sensitive. Even without discussing technical claims that are not visible to me, the practical rule is clear: enter only what is necessary for the task, read each permission or connection request carefully, and avoid rushing through setup simply because the app promises convenience.
If Ditch asks me to connect an account, I would pause and inspect the screen before accepting. I would look for the account being connected, the access being requested, and any choices available to limit or cancel that connection. If I can use the app by entering debt details manually, I would compare that option with the convenience of linking information and choose based on my own comfort level.
This is especially important on a shared phone or a device that other people can access. I would use the device’s normal security protections, avoid leaving sensitive screens open, and sign out or lock the device when appropriate. These are simple habits, but they reduce exposure regardless of which finance app I use.
I would also think carefully before adding debts that belong to another person. A household repayment plan may be useful, but combining personal and shared obligations can make ownership unclear. Keeping notes about who is responsible for each balance can prevent confusion when the plan is reviewed later.
What the free download does and what paid choices mean
Ditch can be downloaded for free, but it includes in-app purchases ranging from $5.99 to $89.99 per item. That makes it important to distinguish between installing the app and deciding whether any optional purchase is worthwhile. I would not pay simply because the app has helped me enter my debts; I would first identify the specific feature or benefit I am receiving and whether it changes my day-to-day results.
Before confirming a purchase, I would check the wording, the billing arrangement, and the cancellation path shown by the store or app. I would also consider whether the paid option improves control, saves meaningful time, or merely adds convenience. Someone with one straightforward balance may not gain enough value to justify spending, while someone managing several debts may place a higher value on advanced organization.
The current version is 1.5.6 and the app requires Android 8.0 or later. That makes compatibility worth checking before planning around it, particularly if you use an older phone. I would also keep the app and the operating system maintained, because finance tools deserve the same update discipline as banking and payment applications.
How I would build a safer repayment routine
I would start with an inventory, not a target. For every debt, I would gather the current balance, required payment, due date, and interest information from the creditor’s own records. Then I would enter the details into Ditch slowly and compare what appears in the app with the original statements. This first comparison is the most important quality check in the whole workflow.
Next, I would set a repayment amount based on a complete monthly picture. That means accounting for rent, utilities, food, transport, insurance, and a small buffer before deciding what can go toward extra payments. If the app encourages a payoff plan, I would use it as a planning aid rather than allowing the plan to dictate an amount that my budget cannot support.
After that, I would choose a regular review day. A useful review is not just looking at a progress bar. I would compare the latest creditor balances with the figures in Ditch, check whether payments posted correctly, and update anything that changed. If a balance fell more slowly than expected, I would investigate the reason instead of assuming the app was wrong or that I had failed.
One non-obvious benefit of this process is that it separates planning from confirmation. Ditch can help me decide what I intend to do, while the creditor account confirms what actually happened. Keeping those roles separate reduces the risk of confusing a planned payment with a completed payment.
When a change in income should change the plan
A repayment plan should be flexible enough to survive an ordinary bad month. If my hours are cut, a repair bill arrives, or another essential cost rises, I would reduce the extra payment rather than borrowing again to preserve an ambitious schedule. The fastest theoretical payoff is not the best plan if it repeatedly causes new debt.
Conversely, a temporary increase in income can be used carefully. I might direct part of a bonus or freelance payment toward the balance while keeping enough for taxes, upcoming bills, and a reserve. The app can help me track the decision, but it cannot determine whether the money has another higher-priority use.
This is where Ditch compares favorably with a static spreadsheet for some users. A spreadsheet can be more customizable, but it requires more maintenance and more discipline to keep formulas and balances accurate. Ditch’s value is convenience and focus. The trade-off is that a spreadsheet may offer greater transparency for people who want to inspect every calculation themselves.
Who should use it and who should choose another tool
I would recommend trying Ditch if you have a manageable set of debts, want a dedicated payoff view, and are willing to review the information regularly. It may also suit someone who has tried keeping repayment notes in a phone app but wants a more purposeful workflow. The focused design can make debt feel less scattered.
I would be more cautious if your finances require detailed household budgeting, investment tracking, tax planning, or business accounting. A debt payoff app is not a substitute for those functions. Someone with irregular income may also need a broader budgeting system before committing to automated payments, because the central challenge is cash-flow timing rather than debt organization.
If you strongly prefer complete manual control, a spreadsheet may be better. It can be slower, but every formula and assumption is visible. If you want official transaction records, the creditor’s own app remains essential. If you need professional guidance because you are behind on payments or facing legal collection activity, a qualified financial counselor is a more appropriate source of help than any automated tool.
My cautious verdict after looking at the whole experience
Ditch has a clear reason to exist: it puts repayment at the center instead of treating debt as one small category inside a general money dashboard. I find that focus useful because it encourages a repeatable habit—collect accurate figures, choose a realistic amount, review progress, and adjust when life changes.
The strongest way to use it is not to surrender decisions to automation. I would use Ditch as a personal control panel, keep official account checks in the routine, and make every connection or purchase deliberately. That approach preserves the convenience of a dedicated tracker without confusing organization with financial advice.
My main reservation is the same reason I would be careful with any finance app: a polished plan can still be based on incomplete or outdated information. The app cannot know every pressure on my budget, and it cannot guarantee that an intended payment has posted until I verify it with the creditor. Users who accept that responsibility will get more from the experience than users looking for a completely hands-off solution.
For me, Ditch is worth considering as a focused debt-management companion, especially for someone who wants structure without building a repayment workbook from scratch. I would start with the free version, enter information cautiously, test the workflow before enabling anything automatic, and delay optional spending until the practical value is clear. Used that way, it can support better habits while leaving the final financial decisions where they belong: with the person who understands the full picture.
Frequently Asked Questions
01What is Ditch: Pay Off Debt Faster, and how does it help with debt repayment?
Ditch: Pay Off Debt Faster is a personal finance app designed to help you organize debts, understand repayment progress, and create a more focused payoff plan. After entering balances, interest rates, minimum payments, and due dates, you can view your overall debt picture in one place. The app is most useful for people who want clearer tracking and motivation while working toward becoming debt-free.
02Can Ditch create a personalized debt payoff strategy?
The app can help you compare and follow common repayment approaches, such as prioritizing the debt with the highest interest rate or paying off the smallest balance first. Your results depend on the accuracy of the information you enter and the payments you actually make. Ditch should be treated as a planning and tracking tool rather than a replacement for professional financial advice or a guaranteed solution to eliminate debt.
03Is Ditch: Pay Off Debt Faster free to download and use?
Ditch may be available to download at no initial cost, but some features can depend on the current subscription model, in-app purchases, or limits placed on the free version. Because pricing and included tools can change, check the app-store listing and subscription screen before starting a trial or entering payment details. Pay close attention to renewal terms, billing frequency, and cancellation instructions.
04Does Ditch connect directly to my bank or credit-card accounts?
Whether Ditch supports account connections depends on the version available in your country and the services integrated into the app. If you manually enter your debts, you remain responsible for keeping balances, interest rates, and minimum payments updated. If account linking is offered, review the requested permissions and privacy policy carefully, and remember that the app should not be used as a substitute for checking official lender statements.
05Is Ditch safe for managing sensitive financial information?
Ditch is intended for personal debt management, so users should review its privacy policy, data practices, and security information before adding financial details. Use a strong, unique password where applicable and keep your phone and operating system updated. Avoid entering unnecessary information, especially if manual tracking is sufficient for your needs, and contact the developer directly if you have questions about storage, sharing, or deleting your data.


